
Navigating auto financing in Columbia, Jefferson City, Moberly, Boonville, and Fulton can feel like navigating the busy intersections along Broadway or Providence Road, but it doesn't have to be overwhelming. Understanding the essential terms like APR, interest rates, and associated fees is vital for making informed decisions about your car loan. Here, we'll break down the differences between APR and interest rates, explain how these rates are determined, highlight common fees, and share tips on improving your financing terms. At Joe Machens Ford, we pride ourselves on providing ethical and transparent financing support, ensuring a smooth journey as you find the right Ford for your needs. So, let's dive in and simplify these concepts together!
What Does APR Mean When Buying a Car?
APR, or Annual Percentage Rate, reflects the total annual cost of borrowing money to finance your vehicle. For Columbia drivers, understanding APR is key to making informed decisions, as it includes not just the interest charged on the loan but also any associated fees.
To clarify, while the interest rate represents the basic cost of borrowing the principal amount, APR provides a fuller picture by incorporating additional lender fees. This makes it a crucial tool for comparing loan offers effectively. A lower APR often translates to lower overall costs. Here's what APR typically includes:
- Interest Rate: The base cost of borrowing.
- Loan Origination Fees: Charges for processing the loan.
- Closing Costs: Fees incurred at the end of the loan agreement.
- Points: Upfront fees paid to lower your interest rate.
- Mortgage Insurance: If applicable, this can be part of your APR.
This is particularly important in light of consumer protections like the Truth in Lending Act, which mandates that lenders disclose the APR. Such transparency allows you to make better comparisons between different loan options, ensuring you choose wisely for your needs.
How Lenders Decide Your Auto Loan Interest Rate
Your auto loan interest rate reflects the cost of borrowing money, influenced by various factors that help lenders gauge your financial reliability. For drivers in Columbia, Jefferson City, Moberly, Boonville, and Fulton, understanding these factors can empower you to secure the best possible rate.
Lenders consider several key elements when determining your interest rate:
- Credit Score: A higher score often leads to lower rates, as it indicates a solid repayment history.
- Credit History: Lenders review your past borrowing behavior to assess risk.
- Loan Amount: Larger loans may result in different rates based on the lender's policies.
- Term Length: Shorter loan terms usually have lower rates, but higher monthly payments.
- Down Payment: A larger down payment reduces the loan amount, which can lower your rate.
- Vehicle Age: Newer vehicles often attract better rates than older models due to their perceived reliability.
For example, if you're considering a Ford Explorer to navigate the snowy streets of Columbia, your credit score and down payment can significantly influence what you pay over the life of the loan. Being proactive about your credit health can lead to more favorable terms. So, whether you're cruising down I-70 or running errands in The District, it pays to understand these factors.
What Role Does a Credit Score Play in Securing a Ford Loan?
Your credit score significantly impacts your chances of securing a Ford loan, determining both your interest rate and loan approval. For drivers in Columbia, understanding how credit tiers work can lead to better financing options and overall savings.
Here's a breakdown of how different credit levels typically affect loan outcomes:
- Excellent Credit (720+): If your score falls in this range, you're likely to receive the most competitive interest rates, which translates to lower monthly payments and less total interest over the life of your loan.
- Good Credit (690-719): Borrowers here can still access favorable rates, though they may be slightly higher than those available to excellent credit holders. This can mean a bit more in monthly payments.
- Fair Credit (630-689): Expect higher interest rates in this category. To enhance your loan terms, consider making a larger down payment, which can help balance the lender's risk.
- Challenging Credit (Below 630): While it can be tougher to secure a loan with a lower credit score, options still exist. Higher interest rates are common, but consistent, on-time payments can set you on a path to improving your score.
For drivers navigating the streets of Columbia-whether it's the local traffic on Providence Road or the busier routes like I-70-having a good credit score can make the process of financing a Ford much smoother. Plus, good credit habits today pave the way for better opportunities tomorrow.
Are APR and Interest Rate the Same Thing?
No, APR and interest rate are not the same. The interest rate is simply the cost of borrowing the principal amount, while the APR (Annual Percentage Rate) encompasses the interest rate plus additional lender fees, providing a fuller picture of borrowing costs. For Columbia drivers, understanding this distinction is crucial for making informed financial decisions.
For instance, if one financing option has a low interest rate but high fees, its APR could be higher than another option with a slightly higher interest rate but no fees. This means that comparing APRs gives you a clearer “apples-to-apples” view of what you'll actually owe over time when looking at offers from various lenders, including Ford Credit.
- Interest Rate: The basic cost of borrowing expressed as a percentage of the loan amount.
- APR: A broader measure that includes interest and most fees, giving you an accurate annual cost of borrowing.
- Why It Matters: APR allows you to compare different loan offers more effectively, helping you find the best deal for your budget.
What Common Fees Are Associated with a Car Loan?
When financing a Ford, you'll likely encounter several fees that can either be included in your loan or paid upfront. Understanding these costs from the get-go helps you budget accurately and avoids any last-minute surprises during the paperwork process, especially for drivers in Columbia where local regulations may apply.
- Documentation Fee: This fee, often referred to as a "doc fee," is charged by the dealership for preparing and filing necessary paperwork related to your vehicle purchase. The amount can vary significantly between dealerships in the Columbia area.
- Title and Registration Fees: These state-mandated fees cover the cost of transferring the vehicle title into your name and registering it with the Missouri DMV. Make sure to budget for these when planning your purchase.
- Sales Tax: In Missouri, you will incur a Highway Use Tax (HUT) upon titling your vehicle. This tax functions similarly to a sales tax and is crucial to factor into your overall costs.
- Loan Origination Fee: Some lenders impose this fee to process your loan application. It's often rolled into the Annual Percentage Rate (APR), affecting the total cost of your loan over time.
Always request a detailed breakdown of all fees associated with your car loan. For additional insights, resources like Kelley Blue Book (KBB) offer comprehensive guides on navigating the car buying process, including a thorough explanation of typical fees.
Strategies to Improve Your APR on a Ford
Securing a better Annual Percentage Rate (APR) can lead to long-term savings on your Ford loan, allowing you to enjoy your vehicle while spending less overall. For Columbia drivers, taking a few strategic steps can greatly enhance your chances of obtaining a more favorable rate when purchasing a Ford Explorer or F-150.
- Check and Boost Your Credit Score: Regularly review your credit report and address any inaccuracies. Consistently paying bills on time and reducing outstanding debt can significantly enhance your score, making lenders more inclined to offer lower rates.
- Make a Larger Down Payment: Putting down a substantial amount upfront decreases the total amount you need to finance. This lowers the lender's risk and can lead to more favorable loan terms.
- Opt for a Shorter Loan Term: While this means higher monthly payments, a shorter term often equates to a lower interest rate, ultimately saving you money on interest over the life of the loan.
- Shop Around for Rates: Don't settle for the first offer. Comparing rates from multiple lenders can help you find the best deal. Local options in Columbia and nearby Jefferson City often have competitive offers.
- Consider Your Vehicle's Make and Model: Certain Ford models, like the F-150, may qualify for special financing incentives, which can lower your APR significantly. Always check for manufacturer promotions.
For additional insights and expert reviews to guide your decision-making, Consumer Reports is a valuable resource.
Frequently Asked Questions (FAQs)
How can I calculate my monthly payment?
To calculate your monthly payment, Joe Machens Ford recommends using an auto loan calculator or consulting with our finance team. They will help you determine payments based on the vehicle price, your down payment, loan term, and expected APR.
What is a good APR in the local area?
A good APR in the Columbia area can vary based on your credit score and current market conditions. Typically, borrowers with excellent credit can secure competitive rates through Ford Credit or local lenders.
Do I have to finance through the dealership?
No, while Joe Machens Ford provides competitive financing options, you have the flexibility to obtain pre-approval from your own bank or credit union if you prefer.
Can I finance a used vehicle?
Yes, financing is available for both new and certified pre-owned Ford vehicles at Joe Machens Ford. However, interest rates for used cars may be slightly higher compared to new models.
What community values does Joe Machens Ford emphasize?
As a family-owned dealership, Joe Machens Ford is committed to building lasting relationships within the Columbia community, ensuring a straightforward, transparent approach to both sales and service.
How can I expect to be treated during my financing process at Joe Machens Ford?
At Joe Machens Ford, the team prioritizes your comfort and understanding throughout the financing process, reviewing agreements with you to ensure clarity and confidence in your choices.
About Joe Machens Ford
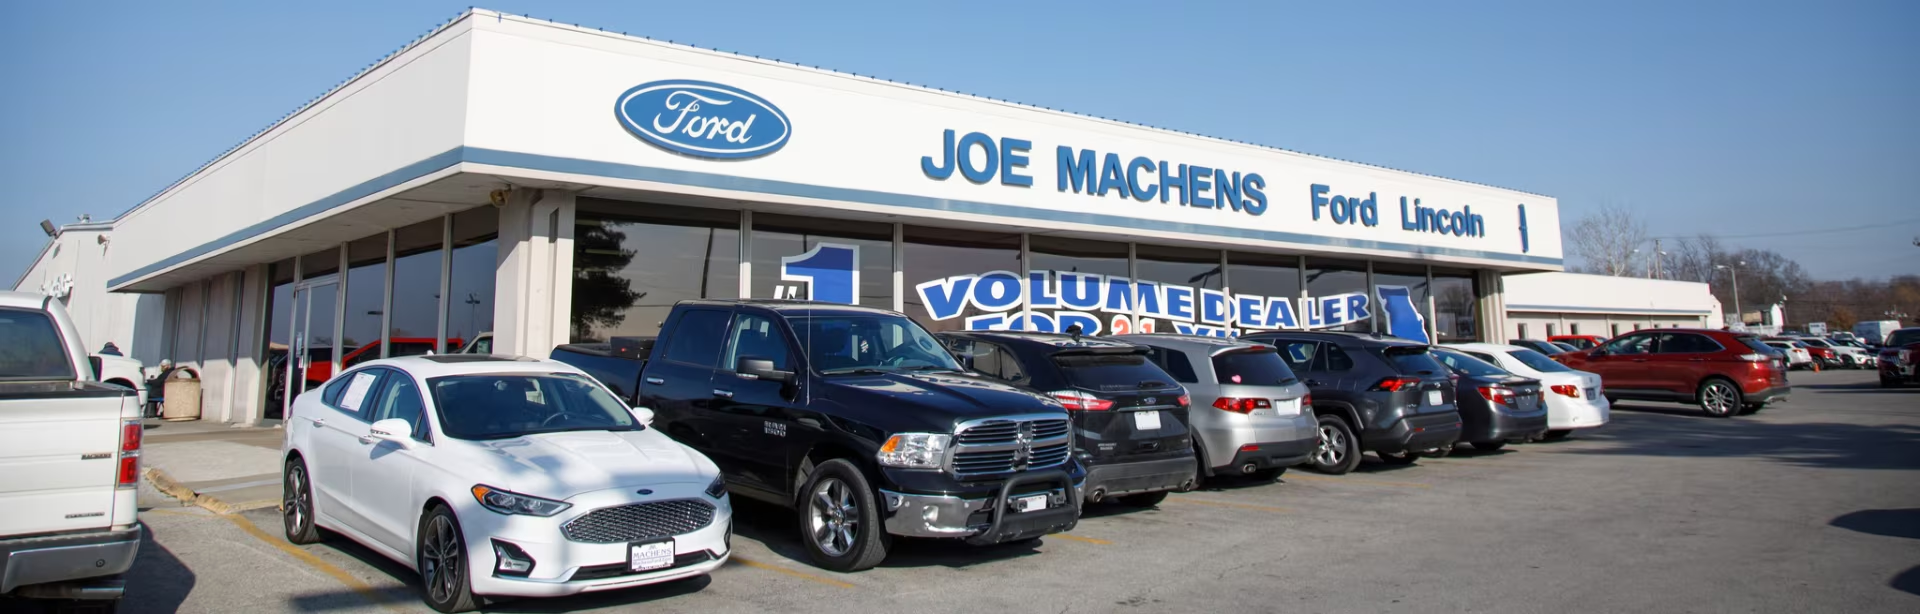
As a family-owned dealership deeply rooted in the Columbia community for generations, Joe Machens Ford is dedicated to building lasting relationships with our neighbors. Our commitment is reflected in our straightforward, transparent approach to both sales and service. We strive to provide a world-class experience that makes you feel like part of our family, ensuring you receive exceptional care every time you visit.
Related Articles:
Choosing Your Columbia Ford Dealer: A Mid-Missouri Driver's Guide